A credit agreement is a contract that can last months or years. Most of us skim it. Reading eight clauses of the credit agreement takes ten minutes and can save real money.
Here is a checklist for any credit agreement.
What should you read first?
Start with the pre-agreement quote, then compare it with the credit agreement. They should match. If the numbers change, ask why before you sign. See the guide to the pre-agreement quote.
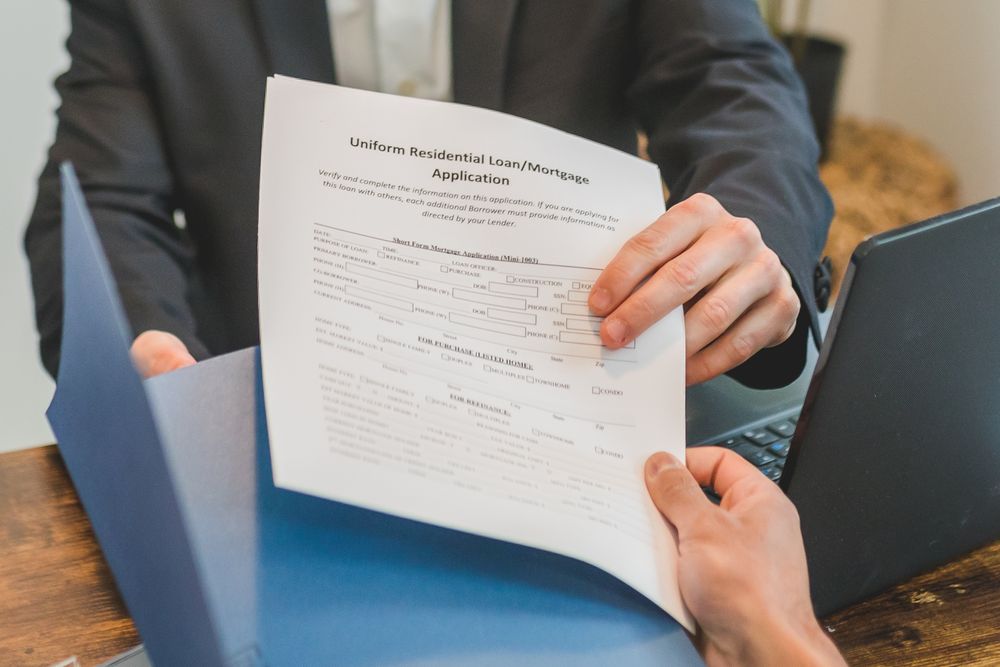
What are the 8 clauses to check in a credit agreement?
| # | Clause | What to look for |
|---|---|---|
| 1 | Amount and payout | The rand amount you receive, after fees deducted |
| 2 | Interest | The rate, fixed or variable, and how it is charged |
| 3 | Fees | Initiation fee and monthly service fee |
| 4 | Total repayment | The full amount in rand you will pay back |
| 5 | Repayment schedule | Number of instalments, amounts and dates |
| 6 | Insurance | Any premium added. See credit life insurance |
| 7 | Default | Charges and steps if you miss a payment |
| 8 | Early settlement | How to settle and what it costs. See settling a loan early |
What does the default clause in a credit agreement really say?
This is the clause people skip. Look for:
- The charge for a late or missed payment.
- How many days pass before the lender sends a formal notice.
- Which address legal notices go to. Make sure it is correct, because a section 129 notice sent to an old address can cost you your chance to respond. See section 129 notices.
If you default, interest and fees on the debt cannot add up to more than the unpaid original amount, under the in duplum rule.
What else should you check?
- Lender details. Name, address and NCR registration number. Check it on the NCR register.
- Notice address. Where legal notices will be sent.
- Debit order terms. The date and the amount. See debit orders.
- Changes to terms. Whether the lender may change fees or rates, and how.
What are the red flags?
Walk away if the lender will not give you a copy to read before signing, if the total repayment is not stated or if you are asked to sign blank spaces.
Also be careful of:
- Pressure to sign immediately.
- Words you do not understand that no one will explain.
- Oral promises that are not in writing.
What are your rights?
- A clear explanation of the key terms.
- A copy of the signed agreement.
- A statement of account on request.
- A way to settle early.
See your rights under the National Credit Act.
What if you already signed and now regret it?
Read the agreement for any cancellation right that applies to your type of contract. Contact the lender quickly.
If you believe the lender broke the rules, see reckless lending.
How do you keep track?
Save the agreement and the quote in one place. Note the repayment dates in your calendar. If your details change, tell the lender.
If you struggle, talk to the lender early. See what to do when you cannot pay your debts.
What do the legal phrases in a credit agreement mean?
South African credit agreements often use formal wording. A few phrases appear again and again, and each carries a real consequence.
| Phrase | What it means in plain English |
|---|---|
| Domicilium citandi et executandi | The address where legal papers will be sent to you |
| Cession | The lender can transfer your debt to another company |
| Cross-default | A default on one agreement can count as a default on another |
| Certificate of balance | A document from the lender that is accepted as proof of what you owe |
| Costs on the attorney and own client scale | You may have to pay the lender’s full legal costs if it sues |
| Surety | Someone else who promises to pay if you do not |
None of these is unlawful, but you should know what you are agreeing to. Ask the lender to explain any phrase in writing, and do not sign until you understand it.
The address clause deserves special care, because a section 129 notice sent to an old address can be treated as properly delivered.
In what order should you read a credit agreement?
Ten minutes is enough if you read in a smart order:
- The first page: the lender’s name, your name and the type of credit.
- The cost table: the amount, the interest, the fees and the total repayment.
- The schedule: the number of instalments and the dates.
- The default clause: charges and notices.
- The address clause: the one for legal notices.
- Early settlement: how it works and what it costs.
- Anything marked “insurance”, “surety” or “cession”.
If something is missing, or if the numbers differ from the quote, stop. Ask for the answer in writing before you sign.
Can you ask for changes to a credit agreement?
Sometimes. A lender may agree to change a debit date, move a repayment, remove an add-on you do not want or correct a detail. You are not obliged to accept the first version. Ask politely and in writing:
“Before I sign, please change the debit date to the 26th, and remove the insurance premium unless I agree to it. Please send me a corrected agreement.”
A lender that refuses reasonable changes may still be the right one, but you now know where you stand. Never sign a page that has blank spaces, and make sure that any change is initialled or reflected in a new document.
What should you do if you sign electronically?
Electronic agreements are valid if they meet the legal requirements, but they are easy to forget. Protect yourself:
- Download the agreement as a PDF before you click “accept”.
- Save the confirmation email or message with the date and time.
- Take a screenshot of the cost table.
- Store everything in one folder, with your payment proofs.
If a dispute comes up a year later, the saved agreement is what the lender has to answer to. Our guide to loan terms explains the words in the cost table.
What should you do once the credit agreement is signed?
Keep the signed credit agreement where you can find it in a year. Check your first statement against the cost table, and make sure the debit order matches the amount and date.
If your address, phone number or employer changes, tell the lender in writing, because notices go to the address on the agreement.
When the last instalment is paid, ask for a paid-up letter and keep it with the credit agreement. If a dispute comes up later, those two documents answer most questions.
Frequently asked questions
Do I have to sign immediately?
No. You can take time to read. A genuine lender allows that.
Can the lender change the terms later?
Only as the agreement and the law allow. Check the clause on changes.
What is the difference between a quote and an agreement?
The quote shows the offer. The agreement is the binding contract. They should match.
Is an electronic agreement valid?
Yes, if it meets the legal requirements. Keep a copy.
What is a domicilium address?
It is the address you choose for legal notices. Notices sent there are generally treated as delivered, so keep it up to date.
Can a lender sell my credit agreement to someone else?
Often yes, through a cession clause. The terms of your agreement should not change, but you would then pay the new owner.
One free 5-minute form is sent to NCR-registered lenders. Each lender decides for itself and shows you the full cost before you sign.
Start my free application